Your Trusted Mortgage Broker in Sydney

Compare home loans from 50+ lenders

No Obligations

MFAA Full Member badge for Phillip Bui, Keystone Home Loans
Google

5.0 Stars Based on 48 user reviews

About Keystone Home Loans

Guiding Sydney buyers through one of life’s biggest decisions

Keystone Home Loans is led by Phillip Bui, our Founder and Principal Mortgage Broker, based in Arncliffe. Phillip helps Sydney families, first home buyers and investors take a smarter financial approach to buying, building, and renovating their homes or investment properties.

Our approach is simple: we get to know you first. We learn about your goals and financial situation, look at how to increase borrowing capacity, then present tailored loan options with a clear recommendation, so you can make informed and confident decisions.

With access to over 50 lenders, Phillip compares your options and negotiates on your behalf to secure competitive rates and the right loan structure. We manage the paperwork from application to settlement and keep you informed every step of the way, with a home loan that supports your long-term goals, not just where you’re at today.

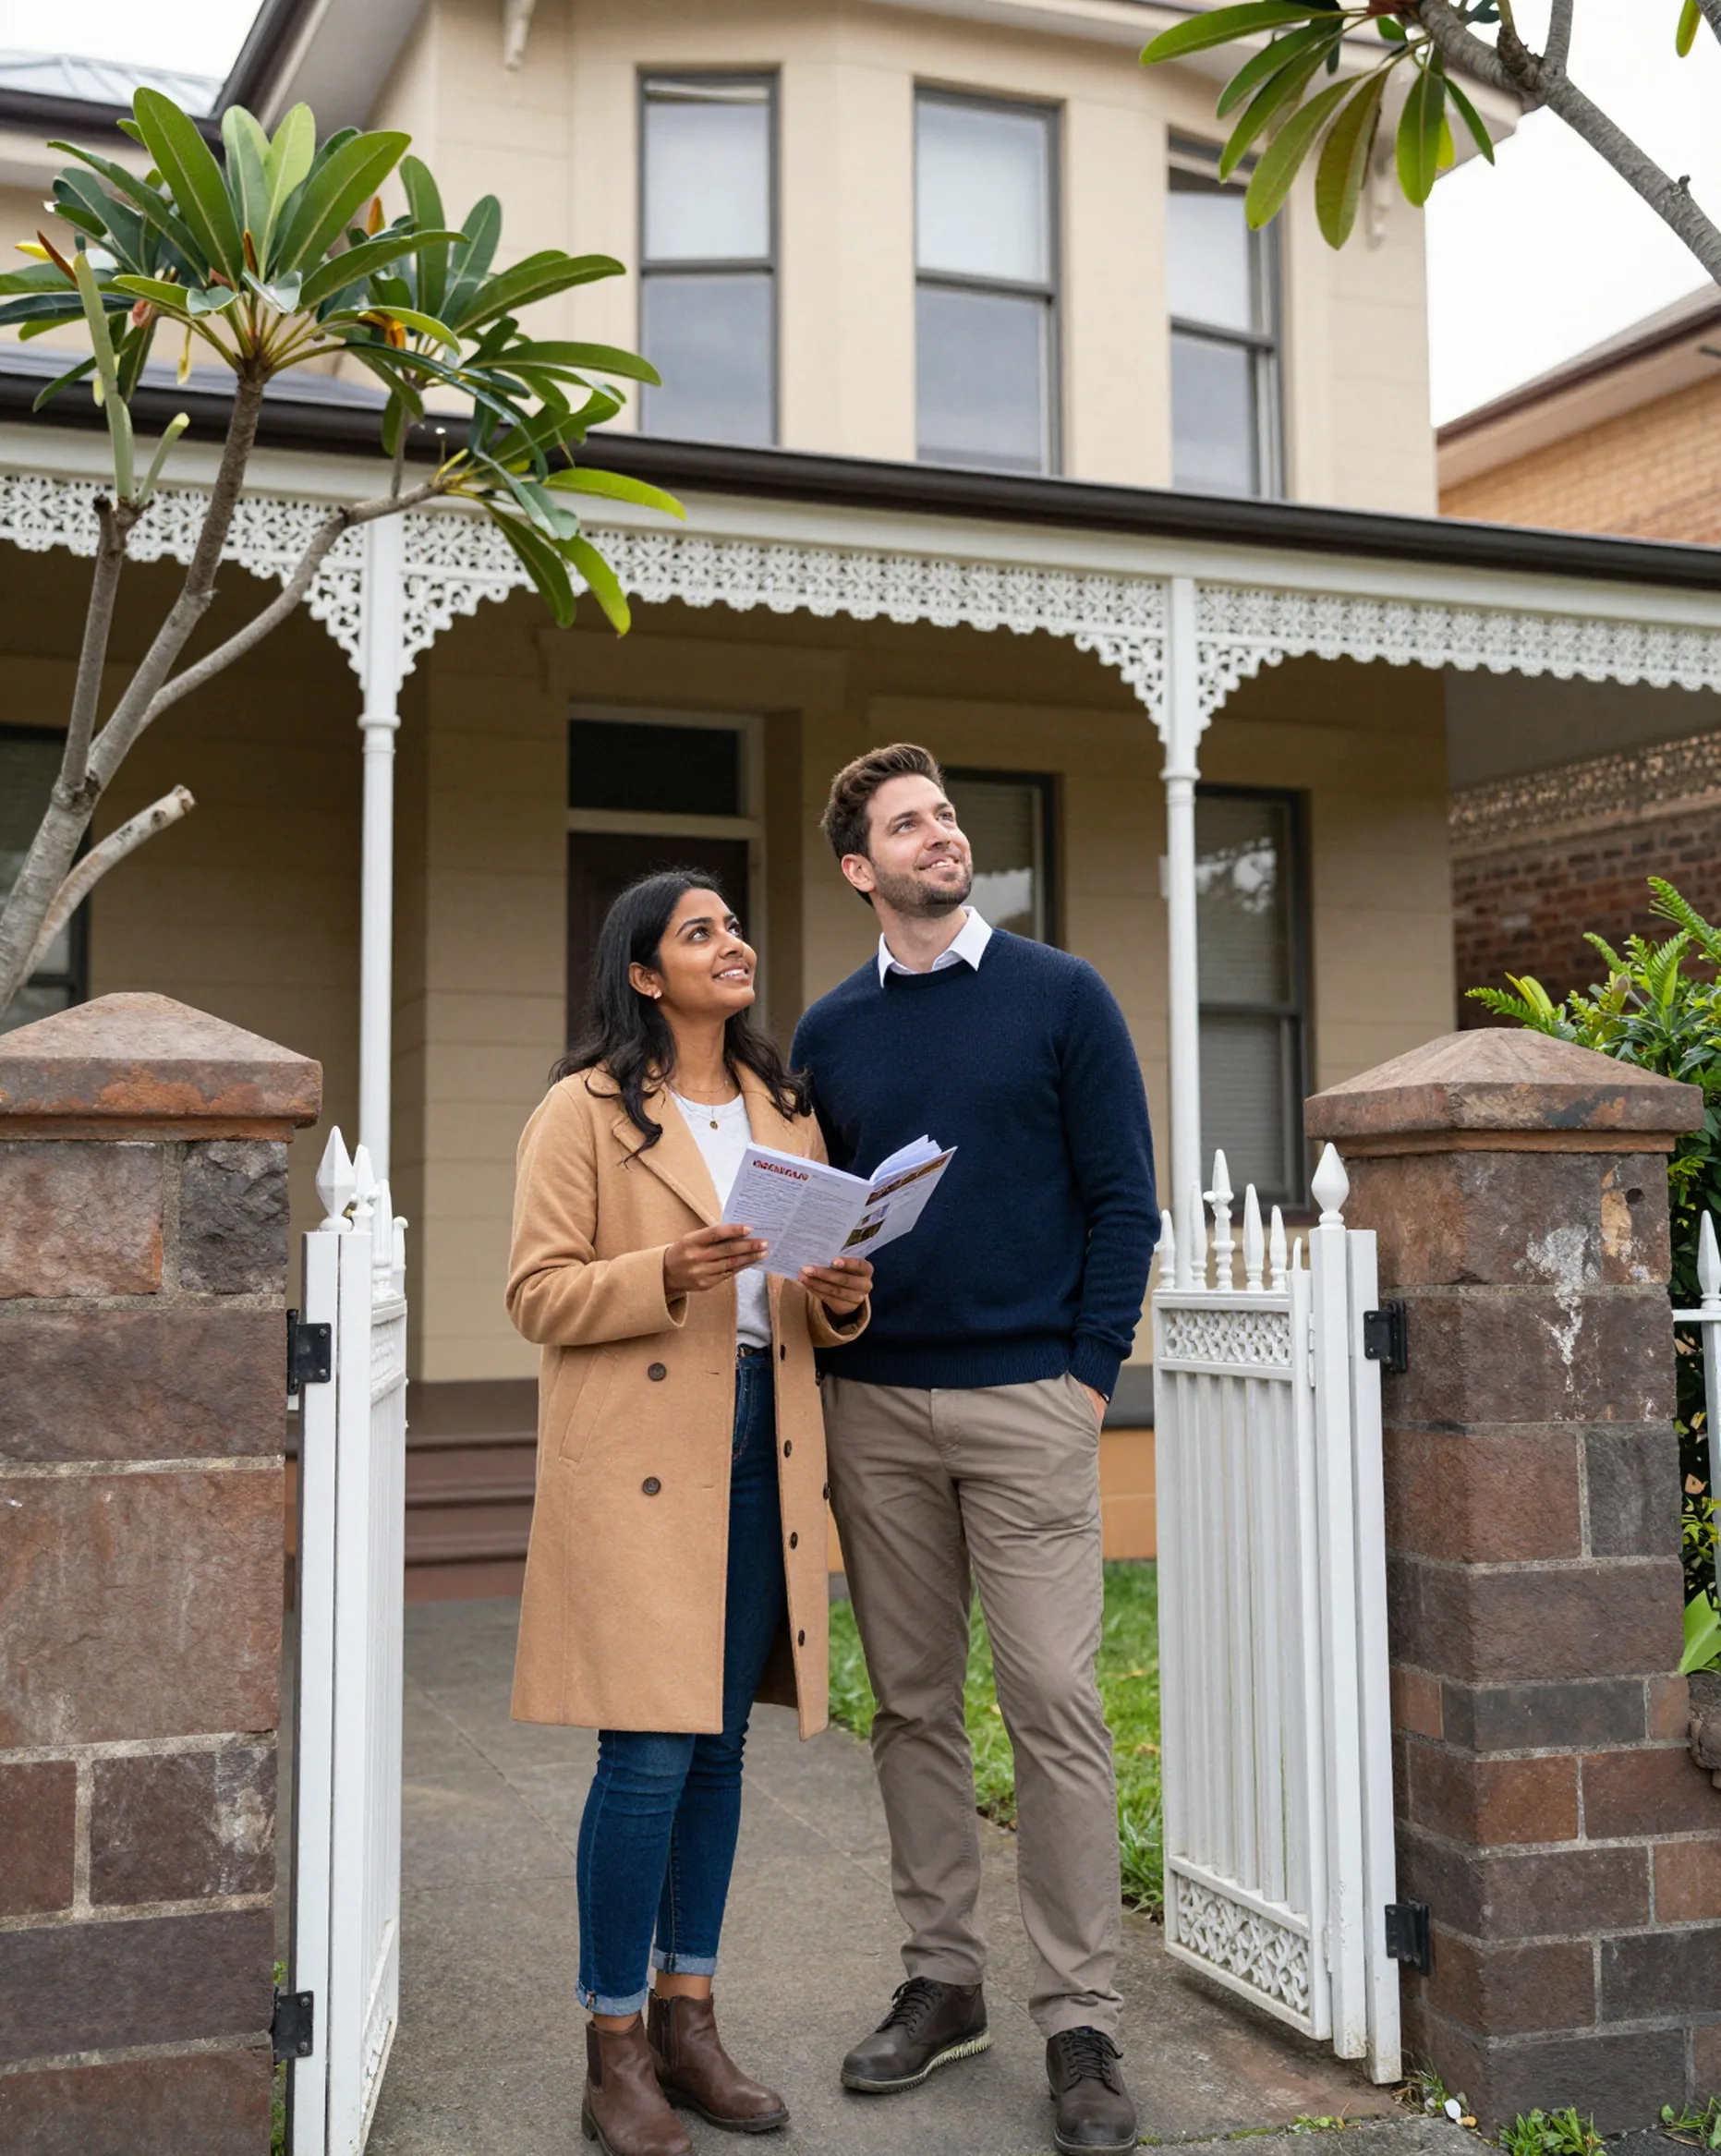
Couple arriving at an open home at a Sydney terrace house

Our services for Sydney buyers

First home buyers

Simplifying your first home journey

Buying your first home is exciting but overwhelming. We guide first-time buyers through tricky lending rules, the first home owners grant, the first home guarantee scheme, and our stamp duty guide, making the process smooth and stress-free.

Clear guidance, no service fee

50+

lenders compared for your first home loan

Free

no-obligation consultation

Bright bedroom in a first home

Rated 5.0 on Google by Our Clients in Sydney and Beyond

Based on 48 Google reviews

Local Expertise

Understanding Sydney’s property market before you commit

Location is everything. Beyond your daily commute, where you buy in Sydney directly impacts your home loan approval and your long-term capital growth. Here are four often overlooked factors to consider before making an offer on a property.
Flood-prone areas

Some low-lying and riverside parts of Sydney are prone to flooding. Checking council flood information and home insurance quotes early helps identify risks before committing, so you are aware of the potential impact of flooding, ongoing insurance costs and resale value.
High-voltage power lines

High-voltage power lines and associated easements run through parts of Sydney. If you're buying a home close to these, be aware some lenders view it as a risk and may limit what you can borrow, and it can affect resale value in the future.

School catchment zones

Buying in a sought-after school catchment zone can support resale value, as many families look to move into areas close to good schools.

Small internal floorspace in high density areas

When buying a unit in a high density area, be aware of small internal floor spaces. Many lenders have minimum size requirements, which may limit what you can borrow, and smaller units can take longer to sell.

50+

lenders compared to get the right loan for your needs

5.0

Google rating from 48 client reviews

Free

no-obligation consultation with Phillip

Buyer Pitfalls

We help you avoid the mistakes most buyers don’t see

Some of the most expensive mistakes buyers make aren’t caused by the market itself. They come from assumptions and oversights during the buying process. Phillip can advise you on the buying process, to help you avoid these issues early.

Not viewing enough open homes

Online listings help, but they don't replace seeing a home in person (we've all seen flattering photo-shopped photos). Aim to attend around 20 open homes in your target area to properly understand real value and what homes are worth paying for. Our how to buy a house guide covers the rest of the process step by step.

Non-compliant renovations

Garages or other spaces are sometimes converted into extra rooms without council approval. While a home may be marketed as having additional bedrooms, this doesn't always align with council records or lender valuations, which can create issues later. Check with your conveyancer or solicitor on this one, or see our how to build guide if you're considering a build yourself.

Trusting the agent

Real estate agents are engaged to represent the seller, not the buyer. While many are helpful, they won't always be upfront with any issues with the property. Buyers relying solely on agent guidance can miss important checks. Make sure you get an independent Building and Pest Report from your own expert, and see our guide on how to make an offer on a house before you negotiate.

Self-employed, looking to refinance, or need to buy before you sell? See self-employed home loans, refinance your home loan, or bridging loans for those specific situations.

Why Choose Us

Why Sydney buyers choose Keystone Home Loans over a bank

Keystone Home Loans

You get a clear strategy, not just a rate.

We compare 50+ lenders, pre-check policy fit, and structure your loan around your goals, so you can buy with confidence, not guesswork.

That includes guidance on borrowing limits, valuations, and the steps that strengthen approval the first time.

With banks or other lenders You’re limited to one lender’s rules and process.

You’ll usually get a single or limited set of options, generic guidance, and slower back-and-forth, especially if your situation isn’t straightforward.

There’s less flexibility to shape the loan structure around your future plans, and more risk of surprises at the valuation or approval stage.

Buying outside Sydney? We also help clients across New South Wales and Australia-wide.
Testimonials

See what our clients say about our service

Google

5.0 Stars

Based on 48 user reviews

Darren W.

Darren W.

“Refinanced through our mortgage broker and couldn’t be happier. Phillip secured us a great interest rate, helped consolidate our loans, and ended up saving us a heap of money each month. Everything was explained clearly and the process was smooth from start to finish. Highly recommend.”

Michael D.

Michael D.

“Phillip was amazing. Not only did he help us find the loan we desired, he was proactive with our conveyancer, the bank and all other parties involved to make sure we had our i's and t's, ticked and crossed. As a first home buyer this was invaluable. Thankyou Phillip for helping us with our first home.”

Julie H.

Julie H.

“Phillip was great to work with! Helped us with refinancing and obtaining the best rate in the market. He was very efficient and made the whole process very easy. Would recommend him to anyone looking for a mortgage broker.”

Frequently Asked, Clearly Answered

The consultation is about understanding your situation and clarifying what your next step should be. We’ll talk through your income, deposit, existing debts and the type of property you’re considering.

We’ll also explain how the home loan process would work for you, what information is needed, and whether it makes sense to proceed now or prepare further before applying.

Borrowing capacity depends on lender credit policy, not just your income and savings.

Key factors include:

  • income type (PAYG or self-employed)
  • existing debts such as credit cards, car loans and HECS
  • living expenses and dependants
  • deposit size and loan-to-value ratio
  • the type of property being purchased
 

In Sydney, things like property type, unit size or location can also affect how lenders assess a loan. We calculate borrowing capacity using current lender policies so the figures hold up later.

A fully assessed pre-approval is an early assessment of your financial position and still requires almost a full loan application. You do this before you buy a property as it helps you understand your price range and negotiate with more confidence, but it isn’t a final decision.

Formal loan approval is when the lender has approved your home loan and the purchase of the property can go ahead. It happens after you’ve purchased your property and you’ve submitted a home loan application to a lender. The lender has assessed your full application, reviewed the contract of sale and completed a valuation on the specific property. If you are actively buying, we focus on preparation and lender selection early so this step is as smooth as possible.

Timeframes vary depending on the lender, the complexity of your situation and how many other applications the lender is working through. A straightforward application can be approved quickly, while a complex one can take longer.

Once your application is submitted, we will advise you on how long it is likely to take, manage communication with the lender, respond to credit questions and follow up on valuations. Careful preparation before submission helps reduce delays and unnecessary back-and-forth.

Lenders require documents to verify identity, income, assets, liabilities and credit history.

Common examples include:

PAYG

  • Two most recent payslips
  • Bank statements for all accounts
  • Drivers licence, Medicare card and passport
 

Self-employed

  • Bank statements for all accounts for you personally and the business
  • Drivers licence, Medicare card and passport
  • Two most recent financial years of tax returns and financials
  • BAS statements
 

We guide you on exactly what is required based on the lender we’re using so you’re not asked for unnecessary paperwork.

In most cases, there is no cost to you. Mortgage brokers are generally paid by the lender after settlement, similar to how banks pay their own lending staff.

If a fee ever applies due to a specific or complex situation, this is explained clearly before any work proceeds.

Yes. Comparing lenders is only part of the process.

We help with:

  • Getting you home loan ready before we apply
  • selecting lenders that fit your situation
  • choosing the right loan type and structure
  • setting up offsets and repayments correctly
  • considering how the loan should work over time
 

We also factor in how different lenders assess the types of properties commonly found in Sydney.

Yes. We regularly help clients review existing home loans to see whether refinancing or restructuring will save you money and allow you to take the next step towards your property goals.

This may include comparing rates, negotiating with current lenders, assessing switching costs and reviewing how the loan is set up. The aim is to ensure your loan still suits your circumstances and saves you money.

Yes. Some property factors can influence lending decisions in Sydney.

These include flood-prone land and insurance costs, proximity to high-voltage power lines, small or high-density apartments and renovations that are not council approved. We help identify these early so they don’t become issues later.

Didn’t find your answer?

Get better access to more lenders

Over 50 different banks and lenders and access to hundreds of different loans.

  • ANZ
  • Commonwealth Bank
  • NAB
  • Westpac
  • Macquarie
  • ING
  • St.George
  • Bank of Melbourne
  • BankSA
  • Suncorp
  • AMP
  • Bankwest
  • Bendigo Bank
  • ubank
  • ME Bank
  • Bank of Sydney
  • MyState Bank
  • Great Southern Bank
  • La Trobe Financial
  • Pepper Money
  • Liberty
  • Resimac
  • Bluestone Home Loans
  • Heritage Bank
  • Qudos Bank
  • MA Money
  • Finsure Loans
  • Hejaz
  • Bank of China
  • Wisr
  • Prospa
  • Bridgit
  • Brighten
  • Paramount

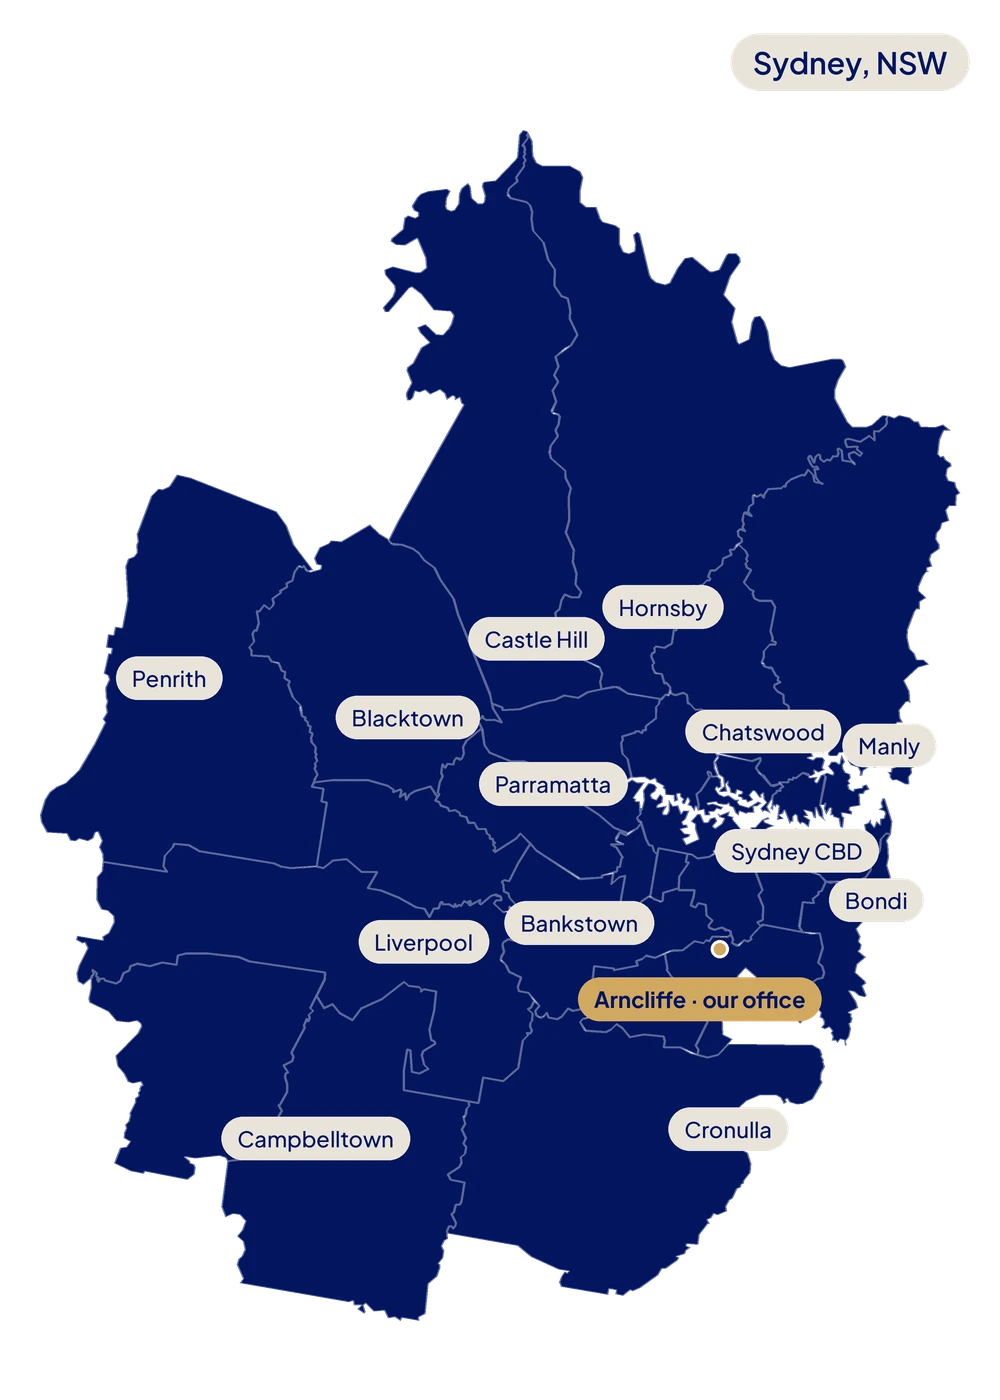
Based in Arncliffe, Sydney

Keystone Home Loans is based in Arncliffe, NSW and helps buyers across Sydney, as well as clients elsewhere in Australia and overseas. Whether you're local or not, we're here to help you achieve your property goals.

  • Based in Arncliffe, NSW - helping buyers across Sydney
  • Phone and email - for clients anywhere in Australia or overseas
  • Direct contact with Phillip - you deal with your broker, no call centres
  • Free consultation - no pressure and no obligation
  • Rated 5.0 on Google - from 48 client reviews

"My partner and I never thought buying a property in Sydney would be possible but Phillip made our dreams become a reality. We are so grateful for everything he has done for us and highly recommend his service!"
Sandy D., Google review